
Get Ready for 2027 Open Enrollment
It’s hard to believe that open enrollment is almost here again. The Medicare Open Enrollment Period starts on October 15, and Marketplace Insurance Open Enrollment begins a couple of weeks later, on November 1.
There continue to be changes to both Medicare and Marketplace insurance. To keep you updated, we have listed the most important ones below, taken from recent articles in Kiplinger’s and Forbes magazines.
2027 Medicare changes
- Stand-alone Part D drug plan options are shrinking. The number of plans has shrunk significantly, from an average of 30 five years ago to 11 last year. If the plan you chose last year is no longer available, you will have to look for a new option.
- Part D premium subsidies end in 2027. The temporary federal relief that was in place in 2025 and 2026 is ending, which means premiums may go up.
- The Part D deductible may go up. If your plan has a deductible, the maximum amount allowed is $700, up $75 from last year.
- The Part D maximum out-of-pocket cap may go up. The allowed cap will rise $300 this year, to $2,400. Plans may or may not have this maximum cap; some will be lower.
- Lower negotiated prices for certain drugs. Continuing the initiative of the 2022 Inflation Reduction Act, 15 medications have had their prices negotiated. These include the GLP-1 drugs Wegovy, Ozempic and Rybelsus.
What to do
- Prepare for higher costs. Be ready to pay more for your prescription drug plan in 2027.
- Review your plan. Compare your current Medicare Advantage or Part D plan with others offered during open enrollment to find the best fit.
- Use free preventive services, such as the annual wellness visit.
2027 Marketplace changes
- Premium increases. As a result of the enhanced premium tax credits ending in 2025, premiums will continue to go up sharply next year. The nationwide proposed median premium will rise around 15 percent, making 2027 the second year of double-digit increases. In South Carolina the proposed increase is 16.6 percent, with individual carriers coming in at varying levels.
- The subsidy cliff continues. The subsidy cliff, reinstated in 2026, will continue in 2027. If an individual or family goes over the amount allowed for coverage by even $1, the entire tax credit is revoked. An individual may earn no more than $63,840, and a family of four no more than $132,000. There are strategies to help avoid this if you are close to the limit, or if you are self-employed with variable income.
- Current plans may end. Insurers may leave a market in any year, so check whether your current plan and carrier will be offered in South Carolina in 2027. It is always a good idea not to let a plan auto-renew, as it may no longer be available, may change significantly, or may not be the best plan for you.
- Maximum out-of-pocket limit increase. The maximum out-of-pocket limit will rise from $10,600 to $12,000. This is the limit on what you must pay before the carrier pays all costs. Not every plan reaches that limit, but many do.
What to do
- Don’t let your plan auto-renew. You could face much higher costs, or miss better options, by letting the Marketplace choose for you. Call us to actively re-enroll into 2027 coverage. Open enrollment runs from November 1 to December 15 for a January 1 start date, and through January 15 for a February 1 start date.
- Accurately project your 2027 income. With the expiration of the subsidy repayment cap, give the most accurate income projection possible when enrolling. If your income changes during 2027, report it to us immediately so we can adjust your tax credit and help you avoid owing money back.
- Consider a high-deductible health plan. If you are generally healthy and want to control premium costs, a Bronze plan that qualifies as an HDHP may be an option. These plans allow you to contribute to a tax-advantaged Health Savings Account.
- Get local assistance. Health insurance enrollment is becoming more complex. Our local certified professionals can help you understand your options at no cost to you.
Get to know your Best team
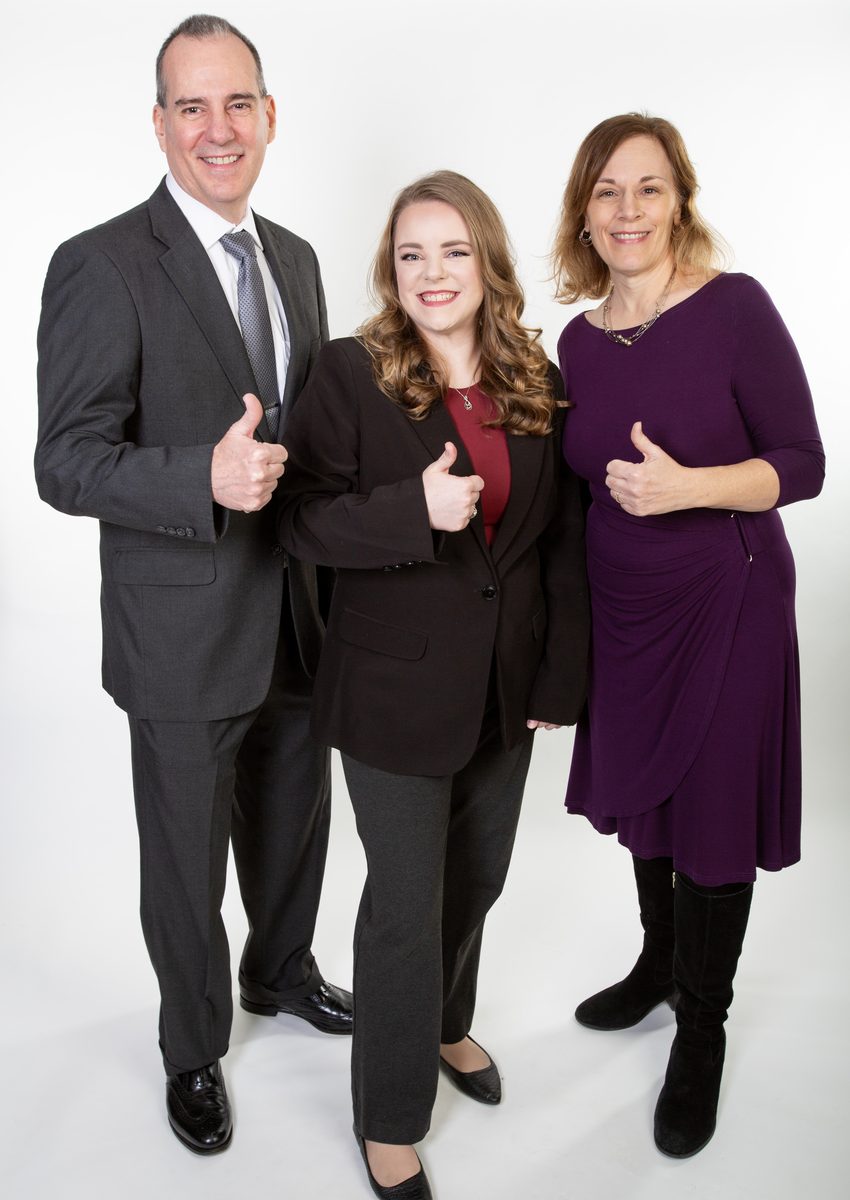
Our agency is a family affair. Some of you know us personally or have been clients for years; others may not know much about us. Here are short bios to help you get better acquainted.
Lauren started Best Insurance in 2016 and is the owner and an agent. Born and raised in Anderson, Lauren graduated with honors from Anderson University with a degree in business administration. She is married to Jared, a first responder here in Anderson County. In her free time she enjoys game nights with friends and family, knitting, and spending time with her black lab, Bentley.
Daniel is Lauren’s dad and Karen’s husband. He was the first insurance agent of the group, launching his career in 2014. Daniel has enrolled many clients into Marketplace insurance over the years, and the 2027 open enrollment period marks his venture into Medicare as well. A lifelong Anderson resident, he has owned several businesses in town.
Karen married Daniel in 2021 and moved back to the Upstate from Hendersonville, North Carolina, where she had lived for almost 30 years. Karen brings decades of administrative and marketing experience to Best Insurance. She enjoys listening to audiobooks, gardening and taking long walks. She and Daniel ride e-bikes regularly, with a goal of visiting every major trail within a five-hour radius.
Slow cooker pulled BBQ chicken and coleslaw
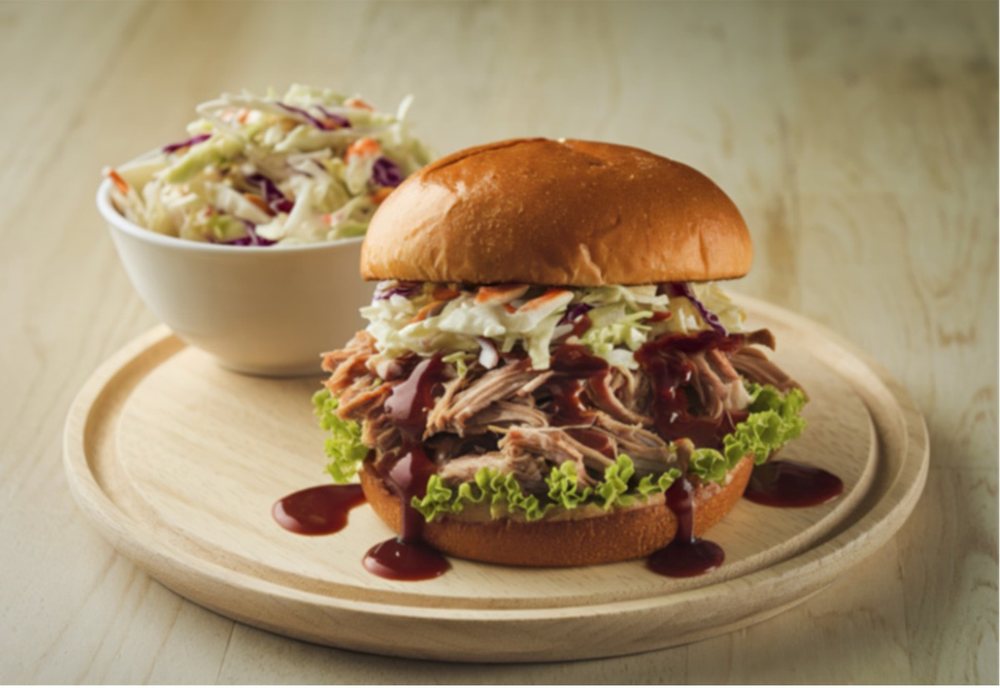
Fall is football season. Whether you watch college games, the pros, or no games at all, this easy barbecue chicken and coleslaw is sure to be a winner.
Ingredients
For the pulled chicken
- 1.5 lbs raw chicken breast
- 1 onion
- 3/4 cup BBQ sauce
- 4 oz unsweetened applesauce
- 2 tsp Worcestershire sauce
- 1 tbsp honey
For the coleslaw
- 8 oz coleslaw mix
- 1/4 cup light mayonnaise
- 1 tsp sugar
- 1 tsp celery seed
- 2 tbsp apple cider vinegar
Instructions
For the pulled chicken
- Combine the BBQ sauce, applesauce, Worcestershire and honey in the bottom of the slow cooker and whisk together.
- Slice the onion.
- Add the sliced onion and chicken breast to the slow cooker, and coat with the sauce.
- Cook on low for 8 hours, or high for 4 hours.
- Shred the meat using two forks.
For the coleslaw
- Combine the mayonnaise, sugar, celery seed and apple cider vinegar in the bottom of a large mixing bowl.
- Add the coleslaw mix and toss with tongs.
Nutrition per serving (1 cup chicken, 1/2 cup coleslaw): 328 calories, 26 g carbohydrates, 37 g protein, 8 g fat, 4 g fiber, 18 g sugar.